Bangladesh Bank to Launch 'Inclusive Instant Payment System' (IIPS): A New Era of Interoperable Digital Transactionsবাংলাদেশ ব্যাংকের ‘ইনক্লুসিভ ইনস্ট্যান্ট পেমেন্ট সিস্টেম’ (আইআইপিএস) চালুর উদ্যোগ: আন্তঃঅপারেবল ডিজিটাল লেনদেনের নতুন দিগন্ত

Bangladesh Bank to Launch 'Inclusive Instant Payment System' (IIPS): A New Era of Interoperable Digital Transactions

Bangladesh Bank to Launch 'Inclusive Instant Payment System' (IIPS): A New Era of Interoperable Digital Transactions

Category: Banking, Fintech & National Economy | Reading Time: Approx. 6–7 minutes

Introduction: The Shift Towards a Cashless Society

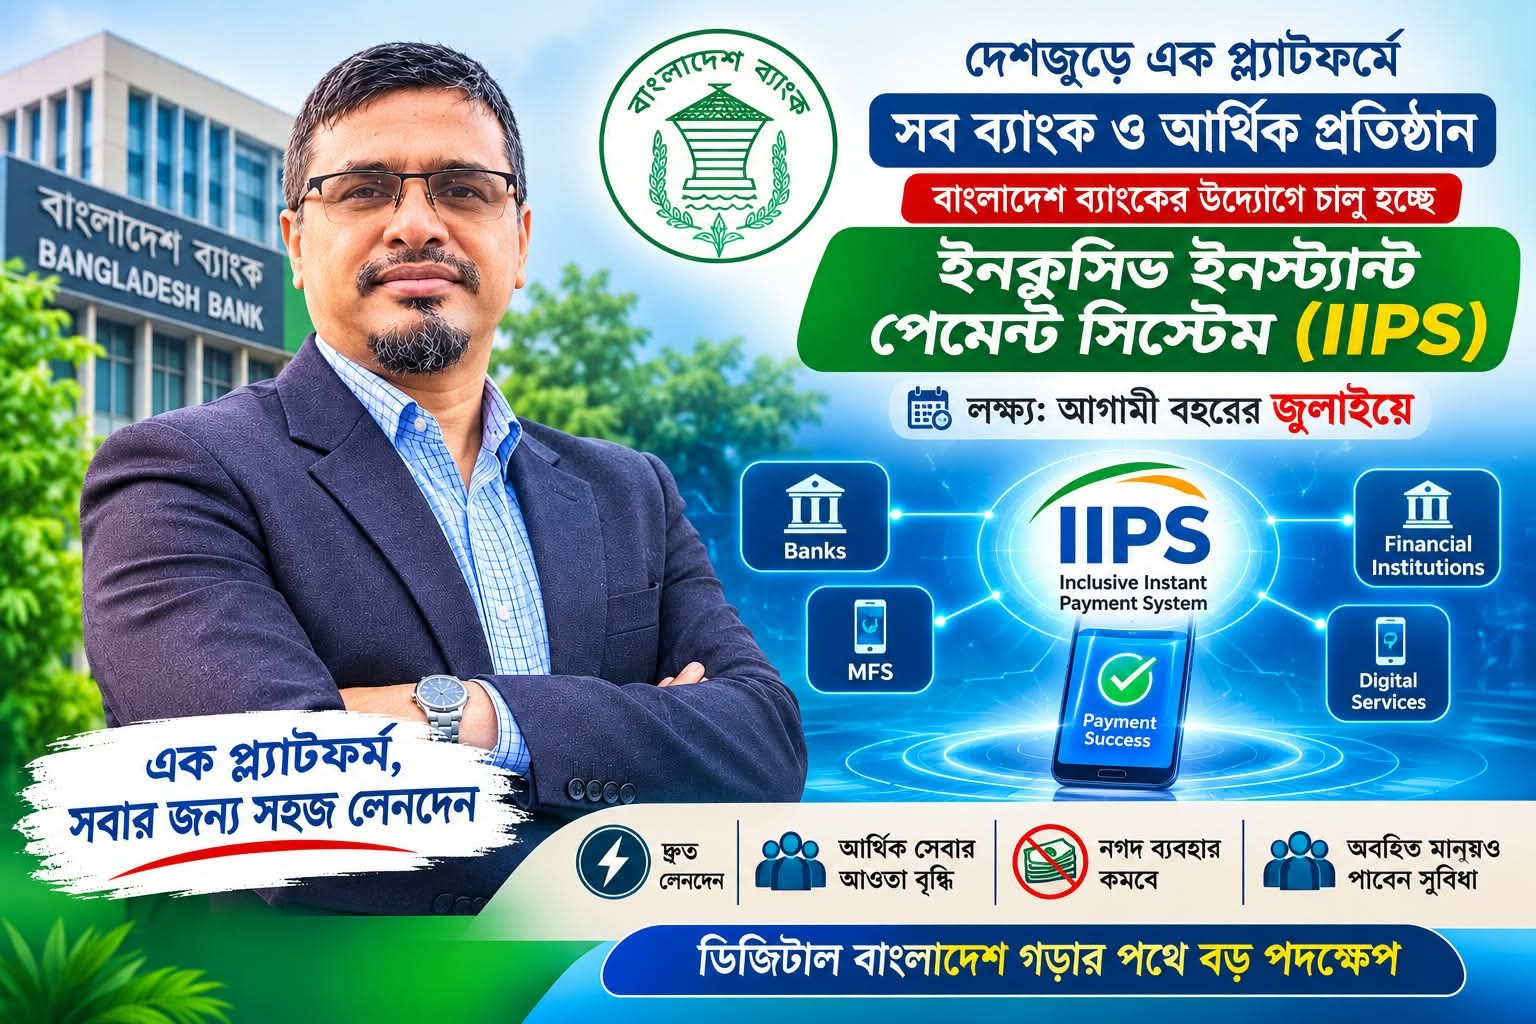
In an era driven by digital transformation, seamless financial connectivity is paramount for national economic growth. Taking a monumental leap forward, Bangladesh Bank has initiated the implementation of the 'Inclusive Instant Payment System' (IIPS). This visionary platform is designed to integrate all commercial banks, Mobile Financial Services (MFS) providers, and various financial institutions into a single, unified digital ecosystem. With a target implementation date set for July of next year, IIPS promises to redefine how citizens manage, transfer, and utilize their funds.

1. What is the Inclusive Instant Payment System (IIPS)?

At its core, IIPS is an interoperable digital payment infrastructure that bridges the gaps between disparate financial networks. Currently, transferring funds across different banks or between a bank and an MFS wallet often involves complex routing, delayed settlements, or separate intermediary networks. IIPS eliminates these barriers.

Under this new framework, consumers will be able to use their accounts or mobile wallets in any financial institution to send money and execute transactions instantly, regardless of the recipient’s provider. This frictionless environment removes the dependency on fragmented, siloed technological architectures.

2. Key Benefits of IIPS for Consumers and Businesses

The introduction of this unified payment gateway brings multifaceted advantages to the national economy:

  • Instantaneous Interoperability: Real-time cross-platform transfers between banks, microfinance institutions, and MFS operators without friction.
  • Reduction of Cash Dependency: By making digital transactions faster and more reliable, the economy will naturally transition away from physical cash, lowering printing and management costs.
  • Enhanced Financial Inclusion: Unbanked and underserved populations will find it much easier to integrate into the formal digital financial grid.
  • Lower Transaction Costs: Standardized infrastructure is expected to reduce operational overheads, potentially leading to more consumer-friendly fee structures.

3. Comparative Impact of the New Financial Architecture

To understand the magnitude of this shift, let us examine how traditional models compare to the upcoming IIPS framework:

Parameter Traditional Banking Framework New IIPS Framework
Inter-Institution Transfers Dependent on separate gateways & clearing houses Unified, instant, and direct interoperability
Processing Time Often requires hours or standard clearing days Real-time (Instantaneous execution 24/7)
Accessibility Fragmented customer experience across apps Seamless cross-wallet and cross-bank usability
Inclusion Scope Limited by institutional boundaries Broadened outreach to the unbanked sector

4. Strengthening Digital Security and Economic Resilience

A centralized digital infrastructure naturally demands robust cybersecurity safeguards. Alongside the technical deployment of IIPS, Bangladesh Bank and regulatory bodies are enforcing stringent data privacy protocols, multi-factor authentication, and encryption standards. Ensuring the safety of consumer data is critical to building public trust in automated clearing systems.

Furthermore, this system aligns seamlessly with national digitalization goals, fostering a competitive fintech environment where traditional banks and agile startups can collaborate and innovate.

Conclusion: Paving the Way for a Smart Bangladesh

The upcoming launch of the Inclusive Instant Payment System marks a defining milestone in Bangladesh's financial history. By breaking down institutional walls and fostering total interoperability, IIPS will accelerate economic velocity, empower micro-entrepreneurs, and streamline citizen services.

As we look forward to next July, the realization of a truly cashless, inclusive, and smart digital economy is closer than ever before.

— Md. Mominul Islam
Founder & CEO, BOSS Solution
দেশের সব ব্যাংক, মোবাইল আর্থিক সেবাদাতা প্রতিষ্ঠান এবং অন্যান্য আর্থিক প্রতিষ্ঠানকে একটি অভিন্ন ডিজিটাল প্ল্যাটফর্মে যুক্ত করতে ‘ইনক্লুসিভ ইনস্ট্যান্ট পেমেন্ট সিস্টেম’ (আইআইপিএস) চালুর উদ্যোগ নিয়েছে বাংলাদেশ ব্যাংক। আগামী বছরের জুলাইয়ে এ ব্যবস্থা চালুর লক্ষ্যমাত্রা নির্ধারণ করা হয়েছে।

ক্যাটাগরি: ব্যাংকিং, ফিনটেক ও জাতীয় অর্থনীতি | পঠন সময়: ৬–৭ মিনিট

ভূমিকা: ক্যাশলেস অর্থনীতির দিকে ঐতিহাসিক অগ্রযাত্রা

ডিজিটাল যুগে দেশের অর্থনৈতিক প্রবৃদ্ধি ও সাধারণ মানুষের লেনদেন সহজ করতে নিরবচ্ছিন্ন আর্থিক সংযোগ অত্যন্ত জরুরি। এই লক্ষ্যকে সামনে রেখে দেশের সব বাণিজ্যিক ব্যাংক, মোবাইল আর্থিক সেবাদাতা প্রতিষ্ঠান (এমএফএস) এবং অন্যান্য আর্থিক প্রতিষ্ঠানকে একটি অভিন্ন ডিজিটাল প্ল্যাটফর্মে নিয়ে আসার উদ্যোগ নিয়েছে বাংলাদেশ ব্যাংক। প্রস্তাবিত এই ব্যবস্থার নাম দেওয়া হয়েছে ‘ইনক্লুসিভ ইনস্ট্যান্ট পেমেন্ট সিস্টেম’ (IIPS)। আগামী বছরের জুলাই মাসের মধ্যে এই যুগান্তকারী ব্যবস্থা চালুর সুনির্দিষ্ট লক্ষ্যমাত্রা নির্ধারণ করা হয়েছে।

১. ইনক্লুসিভ ইনস্ট্যান্ট পেমেন্ট সিস্টেম (আইআইপিএস) কী?

সহজ ভাষায়, আইআইপিএস হলো একটি আন্তঃঅপারেবল (Interoperable) ডিজিটাল পেমেন্ট অবকাঠামো, যা বিভিন্ন আর্থিক প্রতিষ্ঠানের মধ্যকার প্রযুক্তিগত দূরত্ব ঘুচিয়ে দেয়। বর্তমান ব্যবস্থায় এক ব্যাংক থেকে অন্য ব্যাংকে বা ব্যাংক থেকে নির্দিষ্ট কোনো মোবাইল ওয়ালেটে টাকা পাঠাতে গেলে আলাদা নেটওয়ার্ক, দীর্ঘ সময় কিংবা জটিল প্রক্রিয়ার মধ্য দিয়ে যেতে হয়।

নতুন এই ব্যবস্থার ফলে গ্রাহকরা যেকোনো ব্যাংক বা আর্থিক প্রতিষ্ঠানে থাকা নিজের হিসাব কিংবা মোবাইল ওয়ালেট ব্যবহার করে যেকোনো প্রান্তে খুব সহজেই তাৎক্ষণিকভাবে অর্থ পাঠাতে ও লেনদেন করতে পারবেন। এর ফলে ভিন্ন ভিন্ন প্রতিষ্ঠানের মধ্যে অর্থ স্থানান্তরে আর কোনো আলাদা বা বিচ্ছিন্ন নেটওয়ারকের ওপর নির্ভর করতে হবে না।

২. এই উদ্যোগের ফলে সাধারণ মানুষ ও অর্থনীতি যে সুফল পাবে

আইআইপিএস চালুর মাধ্যমে দেশের সামগ্রিক আর্থিক খাতে বহুমুখী ইতিবাচক পরিবর্তন আসবে:

  • তাত্ক্ষণিক ও সহজ লেনদেন: ২৪ ঘণ্টা রিয়েল-টাইমে যেকোনো প্ল্যাটফর্ম থেকে অন্য প্ল্যাটফর্মে তাৎক্ষণিকভাবে টাকা স্থানান্তর করা যাবে।
  • নগদ টাকার ব্যবহার হ্রাস: ডিজিটাল লেনদেন আরও দ্রুত ও নির্ভরযোগ্য হওয়ায় মানুষ ক্যাশ লেনদেন কমিয়ে ডিজিটাল মাধ্যমে অভ্যস্ত হয়ে উঠবে।
  • আর্থিক অন্তর্ভুক্তির সম্প্রসারণ: প্রচলিত ব্যাংকিং ব্যবস্থার বাইরে থাকা বিশাল জনগোষ্ঠী খুব সহজেই ডিজিটাল আর্থিক সেবার মূল ধারায় যুক্ত হওয়ার সুযোগ পাবে।
  • সেবা খরচ কমা: অভিন্ন অবকাঠামো ব্যবহারের ফলে অপারেশনাল খরচ কমবে, যা দীর্ঘমেয়াদে গ্রাহকসেবাকে আরও সাশ্রয়ী করবে।

৩. প্রচলিত ব্যবস্থা বনাম আইআইপিএস কাঠামোর তুলনা

নতুন এই প্রযুক্তির সুফল স্পষ্টভাবে বুঝতে নিচের তুলনামূলক ছকটি সহায়ক হবে:

বৈশিষ্ট্য প্রচলিত ব্যাংকিং ও এমএফএস ব্যবস্থা আসন্ন আইআইপিএস (IIPS) ব্যবস্থা
প্রাতিষ্ঠানিক সংযোগ আলাদা গেটওয়ে ও পৃথক ক্লিয়ারিং হাউস নির্ভর একটি মাত্র অভিন্ন ডিজিটাল প্ল্যাটফর্মে সংযুক্ত
লেনদেনের সময় কখনও ঘণ্টা বা কার্যদিবস সময় নেয় তাত্ক্ষণিক বা রিয়েল-টাইম এক্সিকিউশন (২৪/৭)
ব্যবহারের পরিধি প্রতিষ্ঠানভেদে আলাদা অ্যাপ ও বিধিনিষেধ সার্বজনীন ক্রস-প্ল্যাটফর্ম ও ক্রস-ওয়ালেট সুবিধা
অন্তর্ভুক্তি ক্ষেত্র সীমিত কাঠামোগত পরিধি সারাদেশের unbanked মানুষের জন্য উন্মুক্ত

৪. নিরাপত্তা ও দীর্ঘমেয়াদী অর্থনৈতিক প্রভাব

কেন্দ্রীয়ভাবে এ ধরনের একটি বিশাল ডিজিটাল পেমেন্ট ইকোসিস্টেম গড়ে তোলার ক্ষেত্রে সাইবার নিরাপত্তা এবং ডেটা প্রাইভেসি নিশ্চিত করা অত্যন্ত গুরুত্বপূর্ণ। বাংলাদেশ ব্যাংক এবং সংশ্লিষ্ট নিয়ন্ত্রক সংস্থাগুলো আধুনিক মাল্টি-ফ্যাক্টর অথেন্টিকেশন ও এনক্রিপশন স্ট্যান্ডার্ড বজায় রেখে সিস্টেমটি সাজানোর কাজ করছে।

এছাড়া, এই উদ্যোগ দেশের ফিনটেক স্টার্টআপ এবং ব্যাংকগুলোর মধ্যে সুস্থ প্রতিযোগিতামূলক পরিবেশ তৈরি করবে, যা সামগ্রিকভাবে দেশের ‘স্মার্ট বাংলাদেশ’ বিনির্মাণের স্বপ্নকে আরও ত্বরান্বিত করবে।

উপসংহার

বাংলাদেশ ব্যাংকের এই ইনক্লুসিভ ইনস্ট্যান্ট পেমেন্ট সিস্টেম (আইআইপিএস) চালুর উদ্যোগ দেশের আর্থিক খাতের ইতিহাসে একটি মাইলফলক হয়ে থাকবে। প্রাতিষ্ঠানিক দেয়াল ভেঙে সব সেবাকে এক ছাতার নিচে নিয়ে আসার এই প্রচেষ্টা লেনদেন ব্যবস্থাকে শুধু দ্রুততরই করবে না, বরং দেশের অর্থনীতিকে এক নতুন উচ্চতায় নিয়ে যাবে। আগামী জুলাইয়ে এর সফল বাস্তবায়নের মধ্য দিয়ে ডিজিটাল বাংলাদেশের আর্থিক স্বাধীনতা আরও সুদৃঢ় হবে বলেই আশা করা যায়।

— মো: মোমিনুল ইসলাম (মমিনুল স্যার)
প্রতিষ্ঠাতা ও সিইও, বস সল্যুশন (BOSS Solution)

Mominul Islam

Mominul Islamমমিনুল ইসলাম (Mominul Sir) (মমিনুল স্যার)

An educator, programmer, web developer, SEO expert, ethical hacker, and technical and freelance writer.একজন শিক্ষাবিদ, প্রোগ্রামার, ওয়েব ডেভেলপার, এসইও (SEO) বিশেষজ্ঞ, এথিক্যাল হ্যাকার এবং প্রযুক্তি বিষয়ক ও ফ্রিল্যান্স লেখক।

Comments (0)

Leave a comment

Your comment appears after you verify your email. Email addresses are not displayed.

← Back to News & Blogনিউজ ও ব্লগে ফিরে যান


We are here to Talk to You