Is Digital Transaction Impossible Without bKash and Nagad? The Rise of Smart Banking and Bangla QR
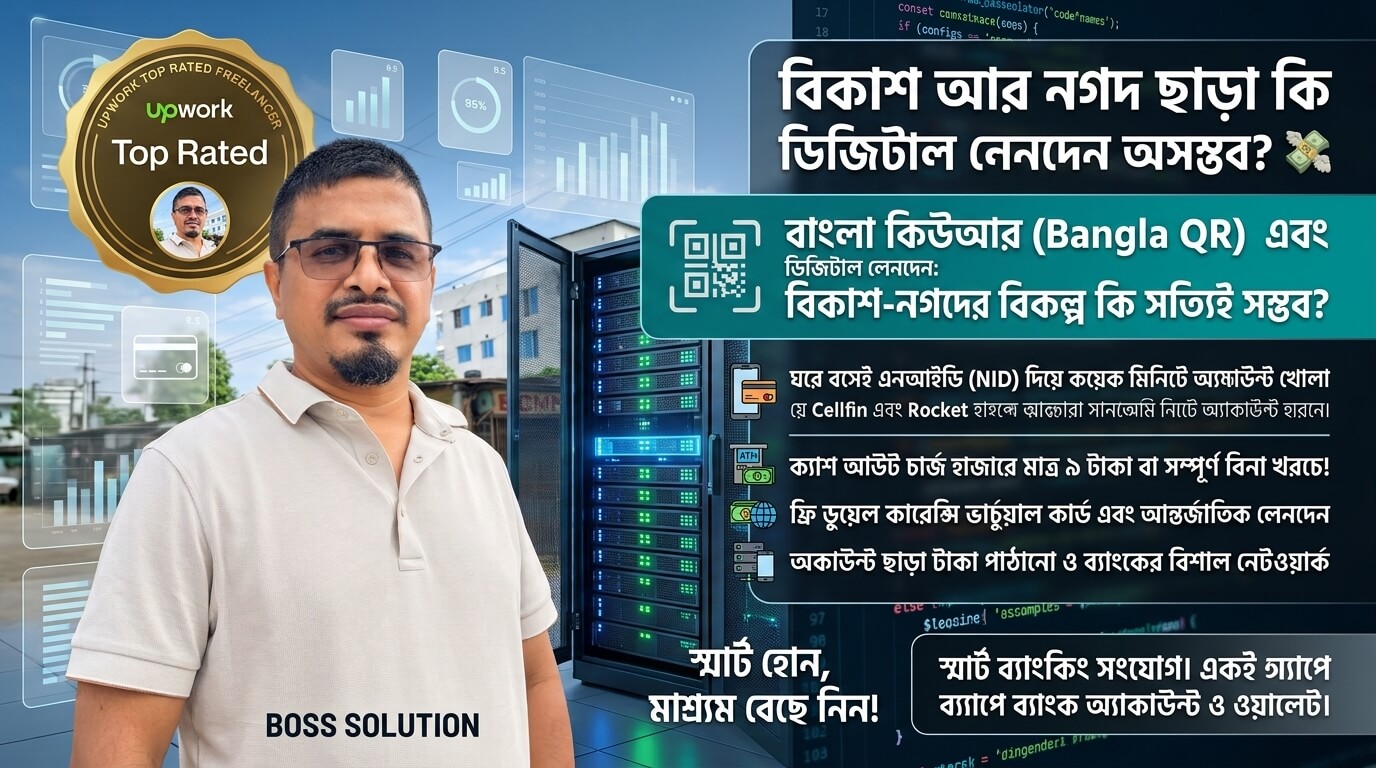
In the evolving landscape of Bangladesh’s fintech sector, a common misconception often dominates discussions: “Digital daily transactions are impossible without MFS like bKash or Nagad.” However, this notion is far from the truth. While universal implementation of Bangla QR has faced reluctance from certain wallet-based providers aiming to retain captive ecosystems, consumers have much more efficient, cost-effective, and powerful alternatives right at their fingertips through modern banking apps.
Banking Apps vs. Traditional MFS: A Practical Comparison
If we look beyond popular MFS platforms, bank-backed applications like Cellfin (Islami Bank Bangladesh PLC) and Rocket (Dutch-Bangla Bank) offer superior, secure, and highly economical financial services without requiring a pre-existing bank account to get started.
Here is why banking-backed apps stand out:
- Easy Account Opening: Just like MFS, applications like Cellfin or Rocket do not require a prior bank account. You can open an account instantly at home using your National ID (NID).
- Zero-Cost Cash Out: While MFS platforms charge roughly 15 to 20 Taka per thousand for cash-outs, Cellfin allows cash-out at 0% charges from any Islami Bank ATM, branch, or sub-branch. Rocket also offers a significantly lower charge (only 9 Taka per thousand via app).
- Free Inter-Account Transfers: Sending money from Cellfin to Cellfin across the country is completely free of charge.
- Dual-Currency Virtual Cards: Cellfin provides a free virtual dual-currency Visa card instantly upon opening, enabling international transactions and online shopping upon passport endorsement.
- Instant Fund Transfers to Any Bank: Through NPSB, BEFTN, and RTGS, funds can be seamlessly transferred to any bank account at minimal cost.
- Institutional Security & Network: Backed by robust banking institutions, these apps provide greater reliability with widespread physical branches and sub-branches acting as support points.
Conclusion
Technology is meant to simplify life, not trap us in high-fee loops. By utilizing robust banking apps and embracing standardized solutions like Bangla QR, we can enjoy seamless, secure, and economical financial services.
Stay smart, choose cost-effective channels.
— Md. Mominul Islam
Founder & CEO, BOSS Solution
বিকাশ আর নগদ ছাড়া কি ডিজিটাল লেনদেন অসম্ভব? বাংলা কিউআর এবং স্মার্ট ব্যাংকিংয়ের যুগ
বাংলাদেশের ফিনটেক সেক্টরে প্রায়ই একটি ভ্রান্ত ধারণা শোনা যায়—“এমএফএস (যেমন: বিকাশ বা নগদ) ছাড়া দৈনন্দিন ডিজিটাল লেনদেন অসম্ভব।” তবে বাস্তবে এই ধারণার কোনো ভিত্তি নেই। ক্যাশলেস বাংলাদেশ গড়ার ক্ষেত্রে সর্বজনীন 'বাংলা কিউআর' (Bangla QR) অত্যন্ত সম্ভাবনাময় হলেও কিছু নির্দিষ্ট ওয়ালেটভিত্তিক সেবার অনীহার কারণে এর সুফল পেতে কিছুটা দেরি হচ্ছে। তবে এর অর্থ এই নয় যে বিকল্প কিছু নেই। সাধারণ ব্যাংক পরিচালিত আধুনিক অ্যাপগুলোর সঠিক ব্যবহার জানলে এমএফএস-এর চেয়ে বহুগুণ সাশ্রয়ী ও নিরাপদ সেবা পাওয়া সম্ভব।
ব্যাংকিং অ্যাপ বনাম প্রথাগত এমএফএস: একটি বাস্তব তুলনা
ইসলামী ব্যাংক বাংলাদেশ পিএলসি-এর ‘সেলফিন’ (Cellfin) কিংবা ডাচ-বাংলা ব্যাংকের ‘রকেট’ (Rocket)-এর মতো ব্যাংকিং অ্যাপগুলো প্রমাণ করে যে কোনো পূর্ববর্তী ব্যাংক অ্যাকাউন্ট ছাড়াই ঘরে বসে এনআইডি (NID) দিয়ে খুব সহজেই অ্যাকাউন্ট খোলা যায়।
কেন সেলফিন বা রকেট সাধারণ এমএফএস-এর চেয়ে এগিয়ে রয়েছে:
- সাশ্রয়ী ক্যাশ আউট: বিকাশ বা নগদে যেখানে প্রতি হাজারে ১৫ থেকে ২০ টাকা চার্জ কাটা হয়, সেখানে সেলফিনের মাধ্যমে ইসলামী ব্যাংকের এটিএম বুথ বা শাখা থেকে সম্পূর্ণ ০% চার্জে ক্যাশ আউট করা যায়। রকেটেও খরচ তুলনামূলক অনেক কম (হাজারে মাত্র ৯ টাকা)।
- ফ্রি আন্তঃলেনদেন: সেলফিন থেকে সেলফিনে দেশের এক প্রান্ত থেকে অন্য প্রান্তে সম্পূর্ণ ফ্রিতে টাকা পাঠানো যায়।
- ডুয়েল কারেন্সি ভার্চুয়াল কার্ড: সেলফিন অ্যাকাউন্ট খোলার সাথেই ফ্রি ভার্চুয়াল ডুয়েল কারেন্সি ভিসা কার্ড পাওয়া যায়, যা দিয়ে পাসপোর্ট অ্যান্ডোর্সমেন্ট সাপেক্ষে আন্তর্জাতিক অনলাইন কেনাকাটা করা সম্ভব।
- অন্য ব্যাংকে সহজ ফান্ড ট্রান্সফার: NPSB ও RTGS-এর মাধ্যমে যেকোনো ব্যাংকে সরাসরি অত্যন্ত কম খরচে টাকা পাঠানো যায়।
- প্রাতিষ্ঠানিক নির্ভরতা: ব্যাংকগুলোর বিশাল শাখা ও উপ-শাখা নেটওয়ার্কের কারণে কাস্টমার কেয়ার বা সেবার পরিধি অনেক বেশি শক্তিশালী ও নিরাপদ।
শেষ কথা
প্রযুক্তির সুবিধা আমরা নেব, কিন্তু অযৌক্তিক খরচের ফাঁদে পা দেব না। যেখানে ব্যাংকিং চ্যানেল এবং আধুনিক অ্যাপগুলো আমাদের বৈশ্বিক ও সাশ্রয়ী সেবা দিচ্ছে, সেখানে অতিরিক্ত চার্জ দিয়ে শুধু নির্দিষ্ট কিছু ওয়ালেটের ওপর নির্ভরশীল থাকার কোনো কারণ নেই।
স্মার্ট হোন, সাশ্রয়ী মাধ্যম বেছে নিন!
— মো: মোমিনুল ইসলাম
প্রতিষ্ঠাতা ও সিইও, বস সল্যুশন (BOSS Solution)
Mominul Islamমমিনুল ইসলাম (Mominul Sir) (মমিনুল স্যার)
An educator, programmer, web developer, SEO expert, ethical hacker, and technical and freelance writer.একজন শিক্ষাবিদ, প্রোগ্রামার, ওয়েব ডেভেলপার, এসইও (SEO) বিশেষজ্ঞ, এথিক্যাল হ্যাকার এবং প্রযুক্তি বিষয়ক ও ফ্রিল্যান্স লেখক।